

In April 2024, U.S. Congress passed the Protecting Americans from Foreign Adversary Controlled Applications (PAFACA). This law requires the “qualified divestiture” of TikTok, the highly addictive video app used by more than 150 million Americans, by its owner, the Chinese technology company ByteDance. PAFACA requires ByteDance to sell its stake in TikTok to a buyer approved by the U.S. president within nine months or face a ban. Although Trump has postponed the law’s enforcement as a negotiating ploy in the trade war with China, the TikTok ban enjoys widespread bipartisan support.
Personally, I am not strongly invested in the fate of TikTok. It seems like a fun portal to watch dance routines, cooking tutorials, and cat videos. But it is fair to question whether its user’s tendency to spend hours a day swiping away does not carry serious costs for their social lives and general cognitive and learning abilities.
Health and safety concerns aside, what is more interesting is what the TikTok divestment bill, motivated as it is by a combination of national security and economic nationalist goals, says about trends in the global economic order in the mid-2020s. From an international and historical perspective, the bill is a remarkable step in state-firm relations. For what PAFACA envisions is one of the largest peacetime expropriations of a foreign-owned company’s U.S. operations in the last century (I say “one of the largest” because the valuation of TikTok is disputed–more on that below).
To call the TikTok ban an expropriation is not to suggest it is unprecedented. There are ample precursors in U.S. history for forced transfers of private property on national security grounds. But PAFACA is nonetheless an important signal for what is afoot in the world economy. Consider what the reactions would be to another country treating a U.S. multinational or tech firm in the way that American lawmakers have acted towards TikTok. In all likelihood this would be seen as a coercive seizure of a foreign private investor. To prove this point, it is sufficient to consult the views of the U.S. government itself.
Coerced Sale as an Expropriation Technique
In the 1960s and 1970s, the nationalization of foreign property by non-aligned countries and developing economies became ever more frequent, from Sri Lanka to Chile and Tanzania to Iraq. But not all these expropriations involved police officers raiding Western company offices or taking direct state control of foreign-owned firms through confiscatory means. Often the involuntary transfer of property happened in a less overtly coercive and more gradual fashion. One such method were laws that forced the sale of private assets to government-backed buyers.
By the early 1970s expropriations of American firms’ foreign assets had become so common that the U.S. government began to formulate standing policies to deal with the matter. The prominence of forced divestment as a form of expropriation is well-illustrated by a 1977 report by the U.S. Government Accountability Office (GAO) titled “Nationalizations and Expropriations of U.S. Direct Private Foreign Investment: Problems and Issues” (available here). Based on intelligence provided by the State Department, the officials who drafted this report to Congress wrote that:
Takeovers of private foreign investments by host-country governments can occur through:
-- 1. Formal expropriation or nationalization, seizure of property with or without compensation.
-- 2. Government intervention into managerial control, without ultimate determination of legal ownership, or Requisition, similar to intervention, but implying temporary government control for a specific public purpose.
-- 3. Coerced sale, government effort to induce owners to sell all or part of their properties to a government entity or to private citizens of the host country, sometimes at lower than market value.
PAFACA’s use of “forced divestiture” is a clear example of the measures under Point 3 – “coerced sale”. Note that expropriation and nationalization do not require a government takeover of a targeted firm: private sector interests may be the beneficiary as well. Nationalization can be public or private, but it is not the same as statization.
Of the 260 cases of expropriation of U.S. investors abroad that GAO and the State Department recorded between 1961 and 1975, a quarter took place through forced divestment laws. Instead of seizing ownership of foreign firms outright, host countries passed laws demanding transfer of the foreign-owned assets to local buyers within a certain timeframe. The technique was especially common in Latin America and the Middle East, where governments routinely forced U.S. mining and oil companies to sell their local subsidiaries to state firms at an affordable price on pain of being confiscated or seized without any compensation at all. The data compiled by the State Department show the extent of this phenomenon.
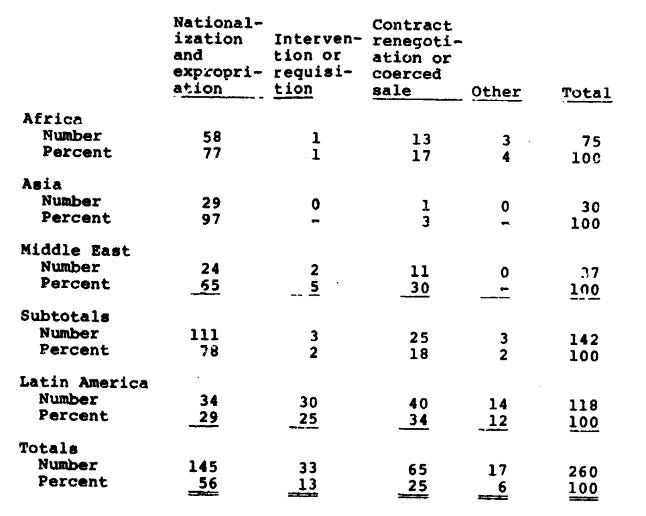
Source: U.S. Government Accountability Office, “Nationalizations and Expropriations of U.S. Direct Private Foreign Investment: Problems and Issues,” (1977) p. 3.
The coercive nature of expropriation did not mean that it was illegal. Even the U.S. government admitted that expropriation was an inherent attribute of sovereignty: every state had a power over property that trumped the rights of private proprietors. In 1625 the Dutch jurist Hugo Grotius called this attribute the “eminent domain” (dominium eminens) of a state. Since the U.S. founders who drafted the Constitution in the 1780s had read Grotius, they used his term to denote the government’s right to take property for public use, enshrined in the Takings Clause of the Fifth Amendment.
By the mid-twentieth century the federal state’s takings power was thus widely accepted in American political and legal thought. It was State Department policy to explicitly recognize that developing countries had a right to nationalization. What mattered was how such procedures were conducted. As GAO wrote:
“The United State recognizes the rights of sovereign states to nationalize or expropriate foreign-owned property, provided such takeovers conform with international law standards which require that the takeovers be for a public purpose, do not discriminate against U.S. citizens, and are accompanied by prompt, adequate, and effective compensation.”
This last phrase introduces another question: if PAFACA is tantamount to an expropriation through forced sale, then what counts as “adequate compensation” for the Chinese owners of TikTok? This hinges on how ByteDance’s property rights in the U.S. operations of the company should be valued. And here the debate around the TikTok divestment has been strangely short on details.
Estimates of the value at stake differ wildly. At the start of the year, some analysts were eyeing numbers “well north of $100 billion”. In August 2025 ByteDance expected that it could fetch as much as $330 billion for TikTok, since its earnings exceeded those of Meta. But just one month ago, Vice-President J.D. Vance cited a value of merely $14 billion, or a price-to-earnings ratio of only 1.4. If ByteDance’s number appears high, Vance’s figure seems an extraordinarily low offer for the company’s exceedingly popular video universe. As one financial adviser quoted by Yahoo commented, Vance’s “suggested value looks like daylight robbery”.
The gap between $14 billion and $330 billion is enormous; a twenty-four-fold valuation difference. Such a gap would hardly ever exist in a normal private-sector sale, where one might quibble over a few multiples’ difference, but hard financial fundamentals would set rough upper and lower limits on valuation. The existence of this vast valuation gap is a telling indicator of the more-than-economic nature of the TikTok affair. It shows that this is a political process through and through, in which the U.S. government’s pressure can drive down the firm’s price, while an improvement in the Chinese negotiating position can help raise it. In other words, we are dealing here with a fully politically determined transfer of property.
A Model for Technology Transfer?
As it happens, it may well be that expropriation is not really what is in store for TikTok. The recent turn in the U.S.-China trade talks suggests that the outlines of a deal have taken shape. Trump’s instinct to do business often takes precedence over the prioritization of national security goals. But it may be that this flexibility could in fact contain some long-term benefits for the U.S. economy.
Under the deal that was reported in mid-September to be in the works, TikTok’s U.S. operations would be acquired by an American investor consortium including the tech firm Oracle, the venture capital firm Andreessen Horowitz, and the private equity firm Silver Lake, who would together own 80 percent of the new entity, with Chinese owners holding the remaining 20 percent stake. The firm’s board would be composed largely of American executives, with one person directly appointed by the U.S. government.
Is this a template for a successful Americanization of TikTok? Perhaps, but there is a catch. For it appears that the app’s essential technological core–the content recommendation algorithm that keeps its users so hooked–would remain dependent on its Chinese creators, and used by the U.S. entity under a special licensing agreement. As The Wall Street Journal reported, “TikTok engineers will re-create a set of content-recommendation algorithms for the app, using technology licensed from TikTok’s parent ByteDance”.
American investors would thus owe ByteDance a continued stream of payments. The Chinese company would share the fruits of its innovation with the American owners. If this deal does transpire, such an outcome would be less an expropriation than a forced technology transfer. As Kevin Xu argued recently in his essay “The TikTok template,” such pragmatic licensing of Chinese technology could pave the way for future tech transfers to the U.S. market by sectors in which the Chinese are now world leaders. As Xu writes:
This is the formula that will likely be applied should, say, BYD want to make a jump into the US market, or CATL want to step up its expansion to supply more US carmakers with its batteries, or Hesai want to ship more LiDARs to US robotics and physical AI companies.
Here there is another interesting way in which the forced divestment bills used by developing countries in the past can help us understand PAFACA. The essential goal of Latin American and African states was not only to acquire national ownership of vital enterprises, but also to gain technological know-how that they could use to advance their own industrial and economic progress. Forced sale laws were not so much about pursuing expropriation as an end in itself, but rather about gaining knowledge that increased national autonomy and control on the world stage. They were simply a tool with which to confront one of the oldest challenges of modernity: how to survive in a world driven by national projects of competitive economic growth.
A video app like TikTok may be relatively unimportant to U.S. economic development. But the same cannot be said for electric vehicles, batteries, and other key elements in the global “electrotech revolution” that is now taking off worldwide. This rapid scaling of renewables and electricity generation, storage and transfer stands to open up vast productive potential as it structurally lowers energy costs for most countries (on the electrotech revolution, see this great report by the think tank Ember).
At a time when U.S. electricity prices are being driven up by climate change, a shortage of electrical and transmission equipment, and AI data center expansion, such reverse technology transfer would be in the immediate interests of U.S. industry and ordinary households. The current political climate may not seem conducive to such win-win compromises. But in the medium to long term the force of economic interests on both sides–China’s need to keep exporting and the U.S. desire to reindustrialize–may well drive policy in this direction regardless.
The Death of the Expropriation Taboo
Does the possible negotiated transfer of TikTok trough a licensing arrangement mean we can shrug off the entire saga as non-consequential? I do not think so. The degree to which U.S. officials, commentators and entrepreneurs have come to see the TikTok ban as a self-evidently just and unimpeachable measure is a telling symptom that we have reached the end of an older consensus about property rights.
During the decades of high neoliberal globalism from the 1980s to the 2010s, one of the great economic sins that states could commit was the coercive dispossession of foreign investors. This is now no longer the case. PAFACA enables the largest capitalist economy in the world to Americanize the most widely used foreign tech company operating on its territory. We have entered a period of much greater state intervention in the private property order, one that will greatly affect international businesses and investors. How to understand that order is going to be the subject of future posts–and an abiding aim of this newsletter more generally.
Non-alignment makes sense again for smaller countries, as I argued earlier in my Substack post:
https://substack.com/home/post/p-167761986
But who would've expected that a big power would find expropriation an acceptable strategy when faced with unfavorable circumstances?
The Dutch takeover of Nexperia seems to be a clumsy version of US expropriation of TikTok resulting in retaliation by China's government. So will the western countries make this the norm against against third world power who have competing interests?